
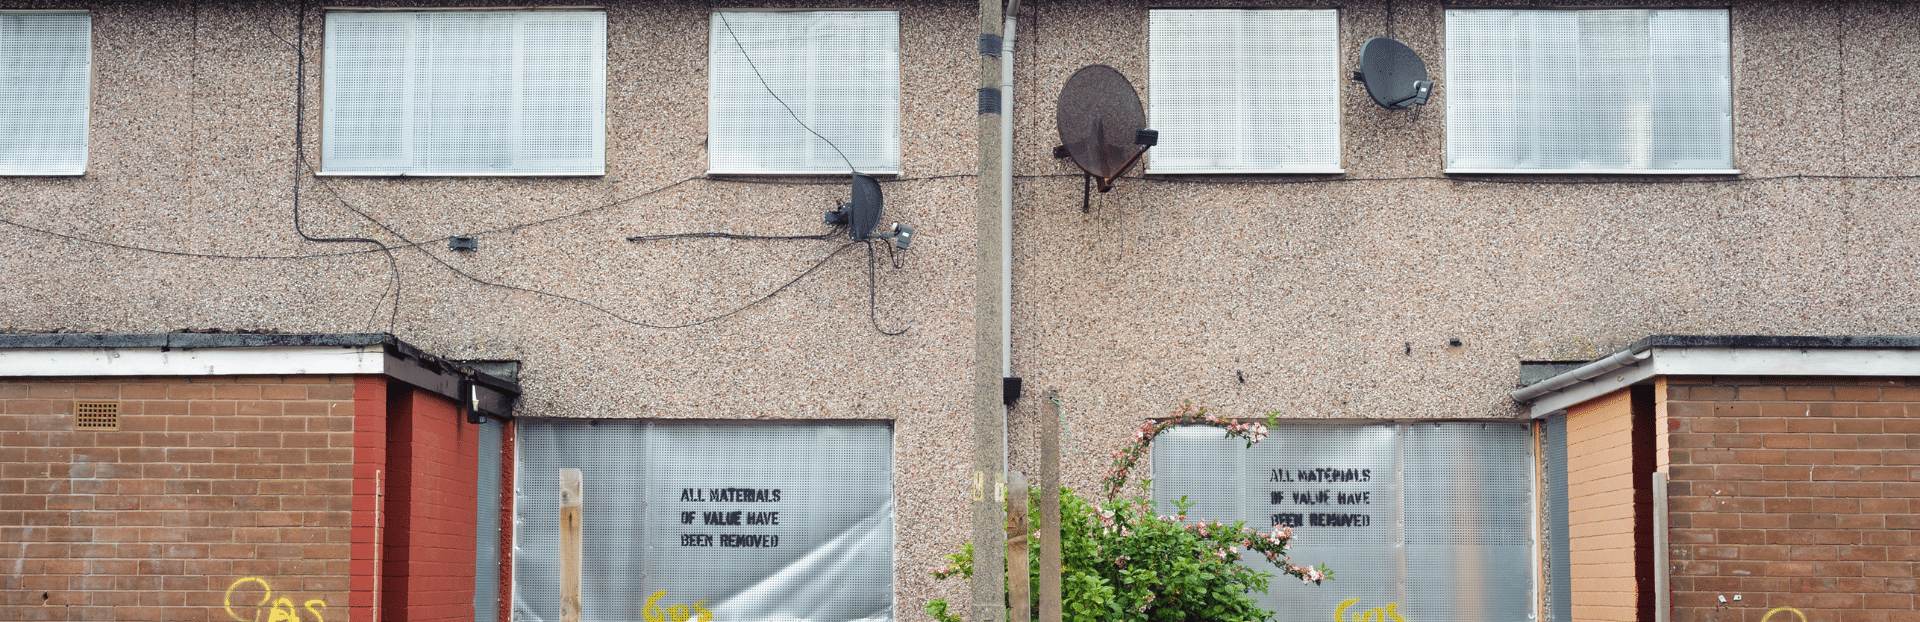
Using a Bridging Loan for Property Development – 7 Things to Know
A bridging loan is short-term property finance, usually repaid within 12 months. Lenders look mainly at the property itself, so developers use it for run-down homes, auction buys and land bought to win planning permission.
Bridging loans are popular with investors using the buy-refurbish-refinance strategy. They are one answer to how to raise property finance for a project, alongside traditional mortgages and bank loans. Because the loan is short-term, the exit plan, selling or refinancing, matters as much as the deal.
Article updated: July 2026
Disclaimer: The information provided in this article about mortgages and bridging loans is for general informational purposes only and should not be considered as financial advice. Property investments and related financial decisions carry inherent risks. Bridging loans, in particular, often come with significantly higher interest rates and fees compared to traditional mortgages. Qualified financial advisers, mortgage brokers and legal professionals are the people who can give advice on property investments, mortgages and bridging loans.
1. Bridging Loans Offer Quick Access To Capital
One of the most significant advantages of bridging loans is the speed at which you can access funds. Unlike traditional mortgages or bank loans, which can take many months to process, bridging finance can often be arranged within days or weeks.
This quick access to capital is invaluable in a fast-moving property market, where opportunities can arise and disappear rapidly. When you find the perfect property for your portfolio, if the seller needs to sell quickly, you may only have a small window of opportunity to complete the sale before it goes to another buyer.
A bridging loan can ensure you have the necessary funds within the deadline, allowing you to secure properties that might otherwise slip through your fingers.
In some cases, it might even be possible to raise 100% of the purchase price through a bridging loan, although this typically requires additional security and significant experience. Making it difficult for 'newer' property developers. This, though, is why a bridge loan for flipping houses is often the financing of choice for experienced developers.
Tip: When seeking a bridging loan provider, be clear about your timeframe and ensure they can deliver within your required timeline. Don't hesitate to ask questions and shop around for the best terms.
2. Bridging Finance Provides Flexibility For Developers
Compared to high-street lending or traditional mortgages, bridging finance offers much more flexibility.
Mainstream lenders often require extensive information about your income and credit history, particularly if you're setting up a property company, before approving a loan.
Bridging finance lenders, on the other hand, are primarily concerned with the property itself, as it serves as security for the loan. This property-focused approach can be particularly beneficial for developers and investors who may not meet traditional lending criteria. It helps those who have a solid exit strategy and significant experience of previous developments, whether their own or from partners in the project.
The repayment terms of bridging loans can often be tailored to suit your needs. However, these loans are typically short-term, usually requiring repayment within 12 months. They also come with higher fees than more traditional financing. For those investors looking to maximise capital growth opportunities, it can be a great solution as long as you have your exit strategy in place.
Tip: While the flexibility of bridging finance is advantageous, having a clear exit strategy is crucial. Whether you plan to sell the property or refinance with a traditional mortgage, ensure you have a solid plan for repaying the bridging loan, otherwise, the costs can skyrocket, with extra fees and pressure put on from the provider.
3. Bridging Loans Can Be Used For Various Property Types
Bridging loans are versatile and can be secured against a wide range of property types. A typical use is to get a house bridging loan to help with a large extension, conversion or wide-scale refurbishment.
This specialist financing can also be used for residential houses, apartments, commercial units, land, and commercial shops, with most developers finding renovation properties needing quick funding as a solution.
That range of property types opens up the market significantly. If you are also flexible about location, there are plenty of options across many of the best property investment areas in the UK.
Whether you're investing in a buy-to-let property, a House in Multiple Occupation (HMO), or a commercial development, bridging finance can be a viable option to consider.
You're also not limited to securing the loan against the property you're purchasing. If you own other properties that are unencumbered (without existing finance secured against them), you can potentially use these as security for your bridging loan. This flexibility can be particularly useful if you are looking to quickly capitalise on a new opportunity while you have equity and capital tied up in other assets.
4. Bridging Finance Can Be Staged Payments
Bridging lenders often pay the money out in stages through a development, rather than all at once. They look at what the project needs to finish and can make decisions quickly. For property developers interested in house flipping, bridging loans (also known in some circles as a house flipping loan) can provide that support when it's most needed.
If you're planning to buy a property to develop and sell on in a short space of time, traditional financing options may not be suitable, have significant restrictions or are not available when you need them most.
Bridging finance can fund a project at whatever stage it has reached. You might have a field with planning permission, be part way through a build, or be in the finishing stages and nearly ready to sell. Funding paid in stages can be crucial for managing cash flow and ensuring your project stays on track.
By using a bridging loan, you can complete work according to your ideal deadlines, potentially reducing overall project time and costs.
Once the development is complete, you can repay the loan through the buy refurbish refinance strategy or by selling the property outright.
Tip: Careful planning is key when using bridging finance for property development. Create a detailed project timeline and budget, factoring in the costs of the bridging loan at each stage, and factor in contingencies and a plan B if the project overruns, to ensure your project remains profitable.
5. Bridging Loans Enable Renovation Of Uninhabitable Properties
One of the most valuable uses of bridging loans in property development is for renovating uninhabitable properties.
If you have ever viewed a run-down property, with no kitchen or bathroom and in clear need of a full refurb, you may start to get excited about all the possibilities. However, understanding what makes a property unmortgageable is crucial.
Many high-street banks and lenders won't provide finance for such projects, viewing them as high-risk investments. This can be frustrating for developers who can see the potential in a property.
Bridging loans can bridge this gap, providing the necessary funds to cover the costs of repairs and renovations until the property reaches a habitable condition. Once the property is renovated, you can either sell it for a profit or refinance with a traditional mortgage. This is a common use case for many property flippers.
This approach can also be particularly effective for the buy-refurbish-refinance strategy, allowing you to add significant value to a property and either keep it as a long-term investment or move on to your next project.
6. Bridge Financing Can Help Add Value Through Planning Permission
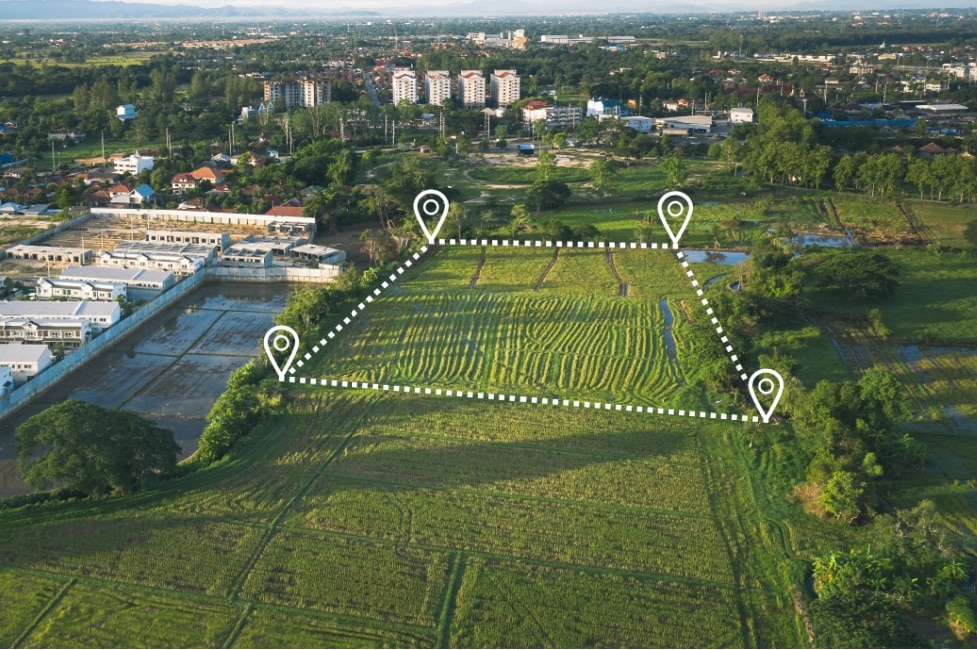
Another strategic use of bridging loans is to purchase land or properties without planning permission, with the intention of obtaining permission and increasing the value significantly.
This is a real high-risk, potentially high-reward strategy that requires careful analysis of local property statistics and market data before proceeding
If planning isn't granted at all, it takes much longer to achieve or planning is granted for a smaller scheme than you hoped, the high cost of the bridging finance can be a real problem for developers.
Many traditional lenders shy away from such projects due to these inherent risks, but bridging lenders are often more open to these opportunities.
With a bridging loan, you may be able to purchase the land or property, apply for planning permission, and then either sell the property at a profit or develop it yourself once permission is granted.
Understanding the property market cycle is crucial, as this strategy can lead to substantial returns when planning permission increases property value.
However, this method isn't for amateur developers; this isn't the best approach if you are buying your first rental property. Often, bridging lenders will require the developer to have significant experience with this very strategy, showing previous successful projects and even providing other assets or properties as security for the loan, as the risk (and costs) are significant.
Tip: This strategy depends on having planning experts, architects and builders on your team, ready to go before you start. They are the people who can accurately assess the true likelihood of a successful planning application, and the true cost of building out the project if planning is achieved. The project needs to be affordable (and profitable) whether you decide to develop it or sell it on to another house builder.
7. Bridging Loans Facilitate Property Auction Purchases
Property auctions can be a great source of investment opportunities, often offering properties at below-market prices for buyers ready to move quickly. Contracts are exchanged immediately, and completion is usually required within 28 days.
Bridging loans are ideally suited for bidding at auction, providing quick decisions and access to funding for these acquisitions.
Using a bridging loan for an auction purchase can reduce much of the stress typically associated with buying this property compared to relying on a high street lender. With the bridging loan already arranged, once you've won the auction and contracts are exchanged, you can focus on your plans for the property, knowing your financing is in place. There's no nerve-wracking daily countdown while a mainstream lender gets through the paperwork.
Tip: If you're considering using a bridging loan for an auction purchase, it's advisable to have your financing arranged before the auction. Many bridging lenders can provide an agreement in principle, giving you the confidence to bid knowing your funding is secure. You do not want to be bidding on a property and exchanging without knowing your funding is ready to go.
FAQs
Can a bridging loan be used for renovations?
Absolutely. The lender will still require security, but for developers converting run-down, derelict homes and requiring funds for a renovation, an empty home grant or a bridging loan for your house renovation can be a great option.
What are the best loans for flipping houses?
There is no single best loan for flipping houses, because every property and every deal is different. On a short-term bridging loan repaid by selling the property, the entry and exit fees matter alongside the monthly rate. On a 6-month term, very high fees can decide whether the flip makes a profit at all.
Ready to buy property?
Browse investment properties with prices and gross yields shown for each opportunity.
See the latest deals